6 Ways to Get Cash From Your Home — and How to Tell Which One Fits You
If you own a home with a low mortgage rate, you're sitting on two valuable things: your equity and your rate. Most ways of getting cash out of a home cost you one or the other. Here are the six common options, the trade-offs of each, and three questions that point you to the one that fits.
To keep things concrete, we'll use one example throughout: a $500,000 home with a $300,000 mortgage at a low fixed rate — $200,000 in equity.
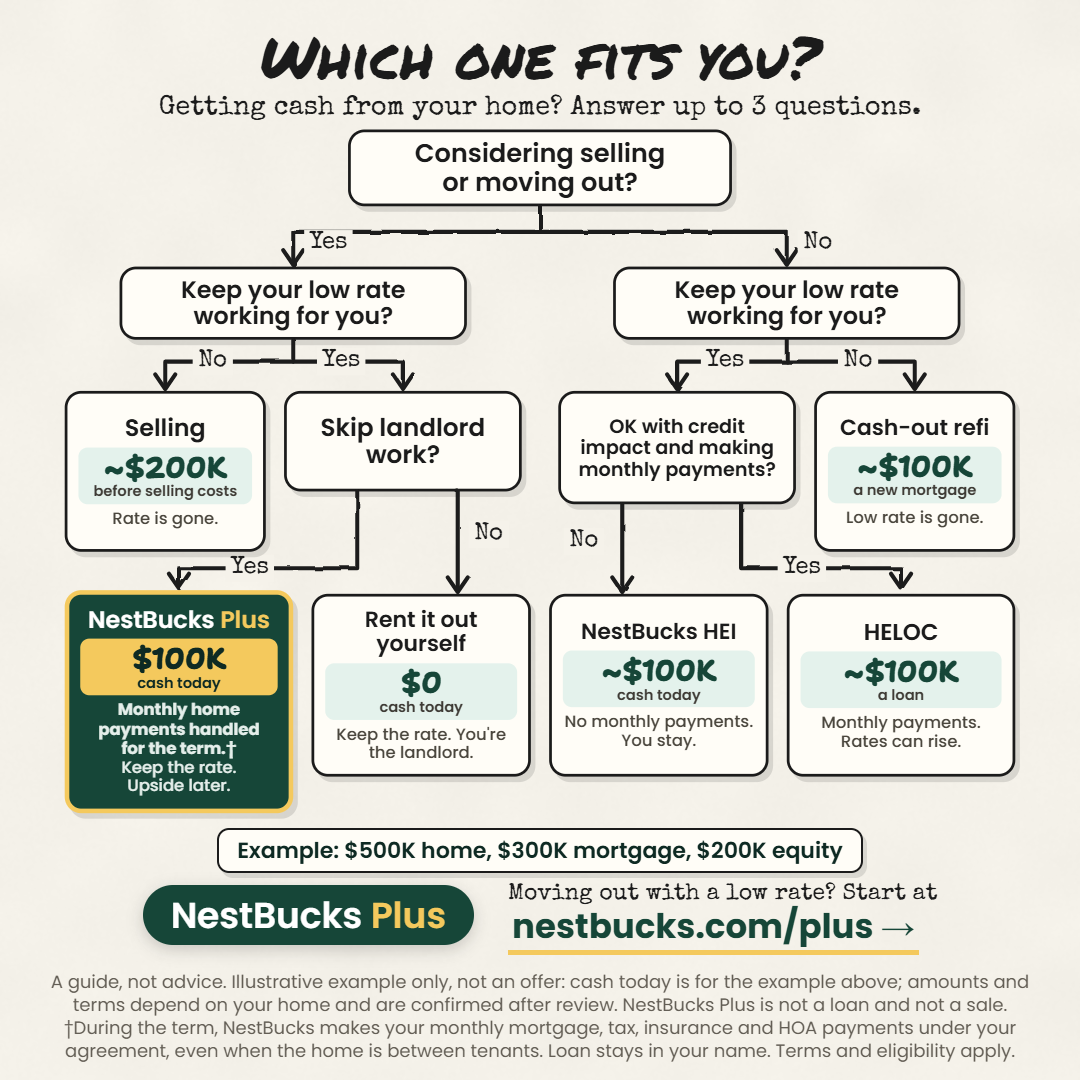
Question 1: Are you moving out?
If you're moving out and want to keep your low rate — and skip being a landlord: NestBucks Plus
NestBucks Plus is built for homeowners who are moving but don't want to give up a low rate. In our example, you'd get about $100,000 in cash today. NestBucks leases and manages the home, and during the term, NestBucks makes your monthly mortgage, tax, insurance and HOA payments under your agreement — even when the home is between tenants.
Like NestBucks HEI, NestBucks Plus has no monthly payments for you, no new loan on your credit report, and no change to your current mortgage — your loan, rate and terms stay as they are, in your name. At least 20% of the home stays yours, so you share in the upside when it sells.
The trade-offs: it's a five-year agreement, there's a one-time fee, and NestBucks shares in the home's future value. NestBucks Plus is not a loan and not a sale. It's starting in Raleigh and Charlotte.
If you're moving out and don't mind being a landlord: rent it out yourself
You keep your rate and your full equity. But there's no cash today, and the tenants, repairs, vacancies and late-night calls are yours to handle.
If you're moving out and don't need the low rate: sell
Selling gives you the most cash — in our example, about $200,000 before selling costs. But your low rate is gone for good, and any future appreciation goes to the buyer.
Question 2: If you're staying, do you want to keep your low rate?
If you'd rather avoid monthly payments: a home equity investment, like NestBucks HEI
You get cash — about $100,000 in our example — with no monthly payments, no new loan on your credit report, and no change to your current mortgage, and you stay in your home. The trade-off: the investor shares in your home's future value when you sell or settle the agreement. It isn't a loan, but it is a claim on part of your home's future value, so read how the settlement is calculated.
If you're OK with a credit check and monthly payments: a HELOC
A home equity line of credit gives you about $100,000 as a loan. You keep your first mortgage and its rate, but you'll make monthly payments, and HELOC rates are usually variable, so they can rise.
Question 3: If you're staying and the low rate doesn't matter: cash-out refinance
A cash-out refinance replaces your mortgage with a new, bigger one at today's rates. If today's rates are higher than yours, you'd pay that higher rate on your whole mortgage — not just on the cash you took out.
The six options side by side
| Option | Cash today (example) | Keep your low rate? | Monthly payments | Main trade-off |
|---|---|---|---|---|
| NestBucks Plus | ~$100K | Yes | None† | 5-year agreement, one-time fee, shares future value |
| Rent it out yourself | $0 | Yes | Yours (offset by rent) | You're the landlord |
| Sell | ~$200K before costs | No | None | Rate and future upside are gone |
| NestBucks HEI | ~$100K | Yes | None | Shares future value |
| HELOC | ~$100K loan | Yes | Yes | Rate can rise; new debt |
| Cash-out refi | ~$100K | No | Yes, on a bigger loan | Whole mortgage moves to today's rate |
Frequently asked questions
Is NestBucks Plus a loan?
No. NestBucks Plus is not a loan and not a sale. Your mortgage stays in your name, and at least 20% of the home stays yours.
Who pays the mortgage on NestBucks Plus?
During the term, NestBucks makes your monthly mortgage, tax, insurance and HOA payments under your agreement, even when the home is between tenants.
Does NestBucks Plus affect my credit or my current mortgage?
NestBucks Plus is not a loan, so there's no new loan on your credit report. Your current mortgage, rate and terms stay as they are, in your name. During the term, NestBucks makes your monthly mortgage, tax, insurance and HOA payments under your agreement.
How is NestBucks HEI different from a HELOC?
A HELOC is a loan with monthly payments and usually a variable rate. NestBucks HEI has no monthly payments; instead, it shares in your home's future value.
Where is NestBucks Plus available?
It's starting in Raleigh and Charlotte, North Carolina.
See your own numbers
No option is right for everyone. Compare the trade-offs with your own numbers. Moving out with a low rate? See your estimate at nestbucks.com/plus.
Illustrative example only, not an offer. Amounts and terms depend on your home and are confirmed after review. †During the term, NestBucks makes your monthly mortgage, tax, insurance and HOA payments under your agreement, even when the home is between tenants. Loan stays in your name. NestBucks Plus and NestBucks HEI are not loans. Terms and eligibility apply. This article is general information, not financial, legal or tax advice.